Eurozone Growth Cools in October as French Instability and Energy Costs Weigh on Markets
Eurozone private sector growth hits a four-month low in October. Discover how French political instability and rising energy costs are impacting the economy.
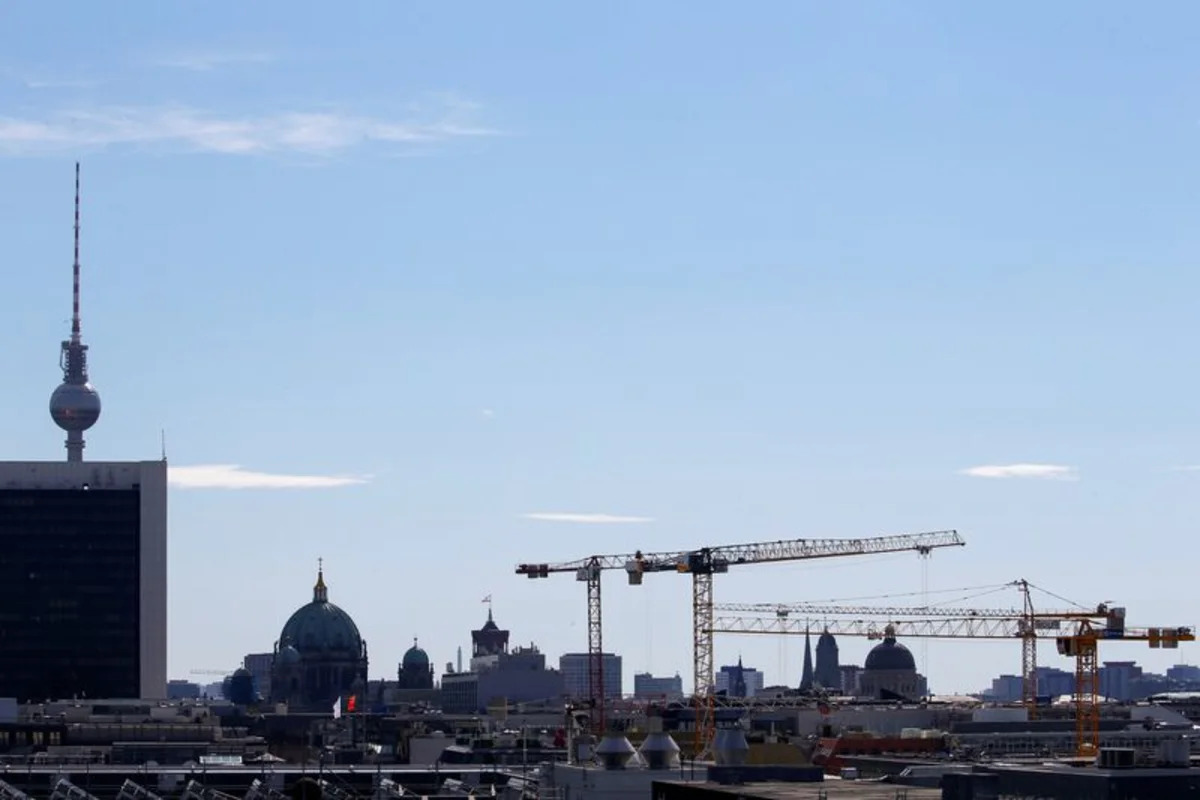
POLICY WIRE — London, United Kingdom — Economic expansion across the euro zone’s private sector decelerated to its slowest rate in four months during October. The downturn was driven by a combination of surging energy-related expenses and a renewed contraction in France, where political and financial volatility have created significant headwinds.
The S&P Global Flash Eurozone Composite PMI Output Index dropped to 51.9 in October, down from 53.1 in September. This figure represents the lowest reading since June and fell short of all projections in a Reuters poll, which had anticipated a more modest decline to 52.7. A reading above 50.0 continues to signal growth, though the momentum is clearly waning.
Rory Fennessy of Oxford Economics noted that after a spring and summer where the euro zone economy defied expectations, the flash October PMIs pour a little bit of cold water on just how much further sentiment could improve. The situation in France remains a primary concern, as government borrowing costs have spiked amid worsening fiscal conditions and heightened political uncertainty.
French business activity contracted unexpectedly this month, fueled by a sharp decline in demand for goods and services. Investors are increasingly wary of the country’s ability to manage its finances, while ongoing street protests have further elevated political tensions ahead of the spring presidential election.
Input costs across the currency union rose for the second consecutive month, largely attributed to the Middle East war and its impact on energy, fuel, and transport prices. Despite these pressures, firms increased their selling prices at a slower pace than in September, indicating a compression of profit margins.
Harry Chambers at Capital Economics observed that while manufacturers are continuing to feel the squeeze of higher energy prices, there is still little evidence of second-round effects, which will be reassuring for the ECB. The European Central Bank is expected to maintain its deposit rate at 2.50% next week, with a 25 basis point hike anticipated in December as inflation remains nearly double the 2% target.
Hiring across the single currency area has nearly stalled, with employment levels showing almost no growth following slight gains in the previous two months. While new export orders rose for the third consecutive month—a positive sign after nearly 4-1/2 years of decline— new orders grew at the slowest rate in the current four-month expansion sequence.
Reporting by Policy-Wire (PW)