Homeownership Costs Surge: Beyond the Mortgage, Expenses Hit Record Highs
Homeowners face rising costs for insurance, taxes, and repairs. Discover how these non-mortgage expenses are straining household budgets across the U.S.
POLICY WIRE — Washington, D.C. — American homeowners are grappling with a significant financial squeeze as the expenses associated with property ownership—excluding mortgage payments—continue to climb. A new report from Zillow released Thursday highlights that these mounting costs are creating a persistent daily cash crunch for families across the country.
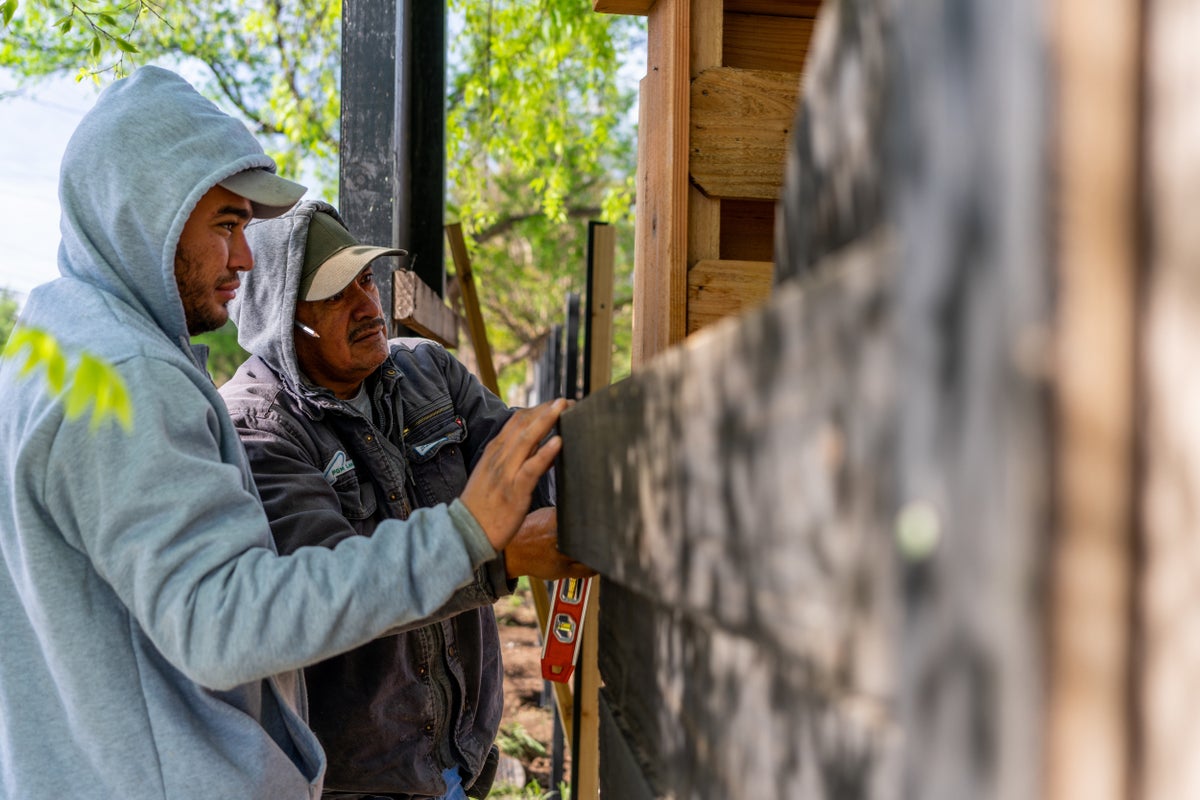
On average, property owners are now shelling out $1,380 every month to cover homeowners insurance, property taxes, and essential home repairs. The data indicates that maintenance remains the most significant burden, with average monthly costs reaching $910.80.
The surge in these expenses is driven by sharp increases over the last five years. According to the report, homeowners insurance premiums have spiked by 54%, maintenance costs have climbed 32%, and property taxes have increased by 19%.
Geographically, the financial impact is uneven. The New York City metro area leads the nation with the highest annual added costs at $25,111, followed by San Francisco at $24,383, Los Angeles at $22,915, and Boston at $22,096. Only two major metro areas saw a year-on-year decline in these costs: Atlanta, which dropped 2.5%, and Seattle, which fell 1.5%.
Despite these challenges, there is a glimmer of hope. The study noted that non-mortgage costs rose at their slowest pace between 2025 and 2026, suggesting that the rapid acceleration of these expenses may finally be cooling.
These rising costs are compounding the broader financial strain on American households. In October, the Federal Reserve reported that 20% of households are currently behind on loan payments—including auto, personal, and home loans—marking the highest delinquency rate since the Great Recession.
Economic pressure remains widespread, with a September survey from Goldman Sachs revealing that over 60% of individuals earning less than $50,000, and 30% of those earning between $50,000 and $100,000, are living paycheck to paycheck. Furthermore, a survey from Self Financial conducted earlier this year found that more than one-third of working Americans have no remaining funds at the end of the month after covering basic necessities.
Nevertheless, the value of homeownership remains a significant pillar of American wealth. In August, total U.S. home equity surpassed $18 trillion, according to data from Intercontinental Exchange. Andy Walden, the firm’s head of mortgage and housing market research, described the milestone as a remarkable achievement that underscores the substantial wealth American homeowners have successfully accumulated.
Reporting by Policy-Wire (PW)