UK Mortgageholders Squeeze as Interest Rates Rise Amidst Global Inflation Fears
Rising Bank of England interest rates are hitting millions of UK households. Discover how mortgage hikes and inflation are impacting families today.
POLICY WIRE — London, UK — The Bank of England implemented its first interest rate increase in more than three years this past Thursday. This move is a strategic attempt to combat surging inflation currently linked to the ongoing conflict in Iran.
Financial analysts suggest that further increases may occur over the next 18 months. The global geopolitical tension continues to drive up costs for energy, fuel, and groceries both domestically and across international markets.
While higher rates can offer better returns for savers, the primary impact is the increased cost of borrowing. Millions of citizens face more expensive expenses for mortgages, credit cards, and personal loans.
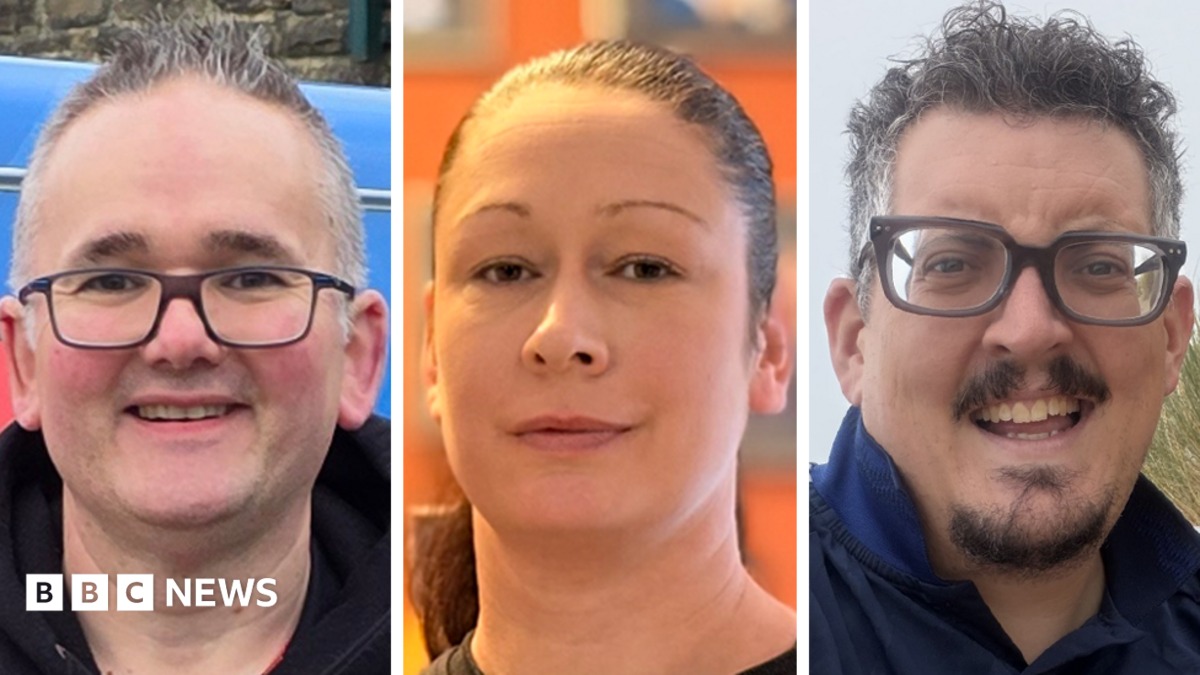
For many, these changes add significant financial strain to households already grappling with the high cost of living. Three individuals recently shared their personal experiences with the shifting economic landscape.
Peter Gill, 48, a resident of Halifax, is among the roughly 1.3 million Britons currently holding variable-rate mortgages. Because these loans fluctuate with the Bank of England base rate plus a lender-specific margin, any policy hike directly increases his monthly obligations.
Gill, who operates a tiling business, noted that his monthly payments will rise by approximately £45 following the recent quarter-percentage-point hike. He expressed concern over future increases, though he believes switching to a fixed-rate deal would currently be more expensive than staying on his existing plan.
The rising mortgage costs coincide with a period where the price of basic goods is climbing. Gill and his wife Faye earn a combined household income of £45,000, and he had to increase wages for his staff due to rising material costs. To manage the family budget, he works six and a half days every week.
Dawn Fazackerley-King, a Pilates instructor near Ipswich, highlighted that while most UK homeowners are on fixed rates, they are not immune to the central bank’s actions. She observed that many people will be shocked by the cost of fixed deals compared to five years ago.
Fazackerley-King had secured a five-year fixed rate of 1.4% which began in January 2022. The best available deal she can find now is 5.69%, which would add roughly £200 to her monthly expenses.
With a joint income of approximately £70,000, she stated she is unsure where the extra funds will come from. Since both she and her husband work full-time, they cannot easily take on additional work while their household costs remain high.
In Shropshire, 41-year-old Ben Thomas transitioned from being a chartered accountant to a paramedic following a mental health crisis during the pandemic. This shift in income left him reliant on personal loans and credit cards for daily survival, resulting in a debt of £52,000.
Thomas has reached an agreement to pause interest on some of his debt, but he remains worried about a £2,000 credit card balance. He and his wife pay £760 toward their mortgage and £300 in monthly debt repayments while battling energy and food bills.
Simon Trevethick, head of communications at the charity StepChange, noted the organization has seen a 20% surge in people seeking assistance this year. He warned that if higher borrowing costs permeate household budgets in the coming months, pressure on those needing help will intensify.
Reporting by Policy-Wire (PW)