How to Fight Mortgage Rates: Expert Strategies to Slice Brutal Interest Costs
Mortgage rates have doubled to 7.18%. Learn how buying points and strategic application tactics can significantly lower your monthly payments today.
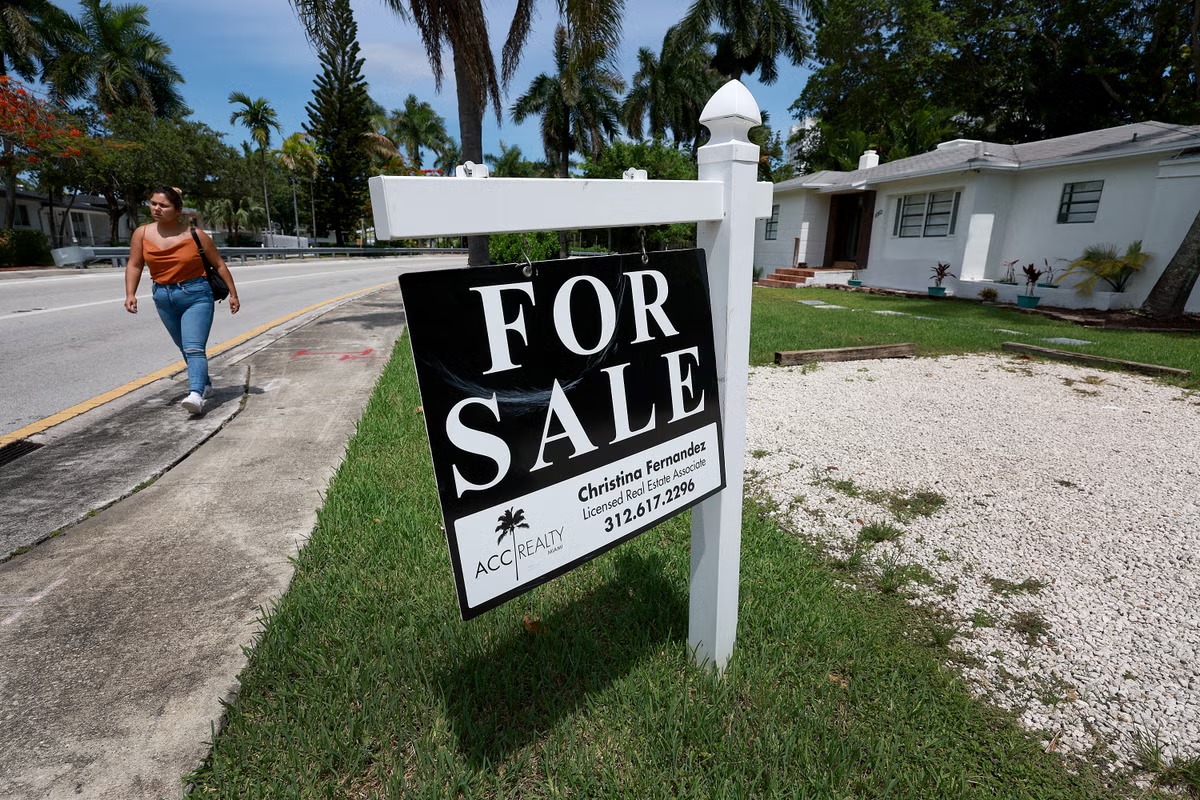
POLICY WIRE — London — Mortgage interest rates have more than doubled since the pandemic began, currently hitting an average of 7.18 percent. This shift has forced new homebuyers into monthly obligations that are hundreds of dollars higher than those seen just five years ago.
Despite these high costs, veteran real estate agents and mortgage brokers suggest that buyers should not lose hope. They argue that a strategic approach to the application process can result in significant rate reductions.
Robert Shamie, CEO of mortgage lender Fidelity Residential, emphasizes that success in this climate depends on combining specific tactics with the right mindset. He advises potential buyers to view themselves as savvy shoppers rather than merely loan applicants.
Just as retail consumers compare prices across different stores to save money, home buyers must apply the same diligence. A typical home purchase involves two major financial hurdles: the long-term home loan and the upfront down payment.
While many believe a large down payment is the top priority because it reduces the loan amount, experts suggest that extra cash might be better utilized toward “points” instead.
Mortgage points refer to the interest rate of a home loan, expressed as a percentage, where one point equals one percentage point. In certain scenarios, borrowers can pay an upfront fee to the lender to secure a lower interest rate. For instance, paying an additional $15,000 could potentially drop an interest rate by one full percentage point.
Buying these points can often result in greater long-term savings compared to negotiating a lower purchase price or increasing the down payment. Mortgage and real estate professionals note that this practice is formally known as buying points.\
Reporting by Policy-Wire (PW)